Wadeem Gardens, and what is now on the table
The sizes, prices, amenities and payment plan come from Modon's own factsheet and payment plan, dated 14 September 2026, and from Modon's masterplan. Where a figure is my own view rather than theirs, it says so. Set the currency and the area unit at the top and the whole page follows you.
What Modon has confirmed
Three gated villa clusters, a choice of Arabian and Modern facades, and two floor plans, Option A and Option B, for every type. 1,094 villas in total: 634 four bedroom, 331 five bedroom, 129 six bedroom. Built-up areas of 430, 510 and 591 sq m on plots of 532, 630 and 720 sq m. Prices from AED 8.7m, 10.2m and 11.6m. A 25 / 75 payment plan, subject to off-plan mortgage approval, with instalments six-monthly from month 8. UAE nationals receive a 5% rebate from Modon, non-transferable.
What is still open
Modon's payment plan does not use the word handover. On both routes the 55% balance falls at month 56, June 2031, and this page treats that as handover throughout. I have asked Modon to confirm it in writing, and I would not treat the date as fixed until they do. Plot-by-plot pricing, orientation and the premium for a park or spine frontage are not published. The resale threshold is not published either, but it has been 20% across every release on this island, so 20% is what this page works to.
The mortgage terms sit with the bank rather than with Modon, so the rate and the structure are a separate conversation and not part of this document.
What I would say about it
Every release Modon has brought to Hudayriyat has sold out. This one asks for 5% to reserve and 20% in total by June 2028. From there a bank funds the next four instalments and the buyer pays interest only on them. Every mortgage in this country is capital repayment, so that is new, and it is the part people will miss.
At AED 8.7m for 430 sq m of built-up area, this is priced inside the band Modon has already achieved on this island, on an island that will look very different by 2031.
What is actually being built at Hudayriyat
Nobody lives here yet. It is a construction site with a beach club on it, and that is precisely the point: you are buying into what it becomes, not what it is. These are the amenities Modon lists against Wadeem Gardens itself.
Drive times as published by Modon. My own off-peak runs are quicker than that: Downtown Abu Dhabi and the Sheikh Zayed Grand Mosque in about 10 minutes, ADGM in 20, the Louvre and Saadiyat in 25.
Wadeem Gardens, inside and out
Tap any image to open it full screen, then swipe left and right on a phone, or use the arrows and your keyboard on a desktop. Filter by villa type, by facade, by the interiors or by the floor plans.
The retail destination is the thing that changes everything
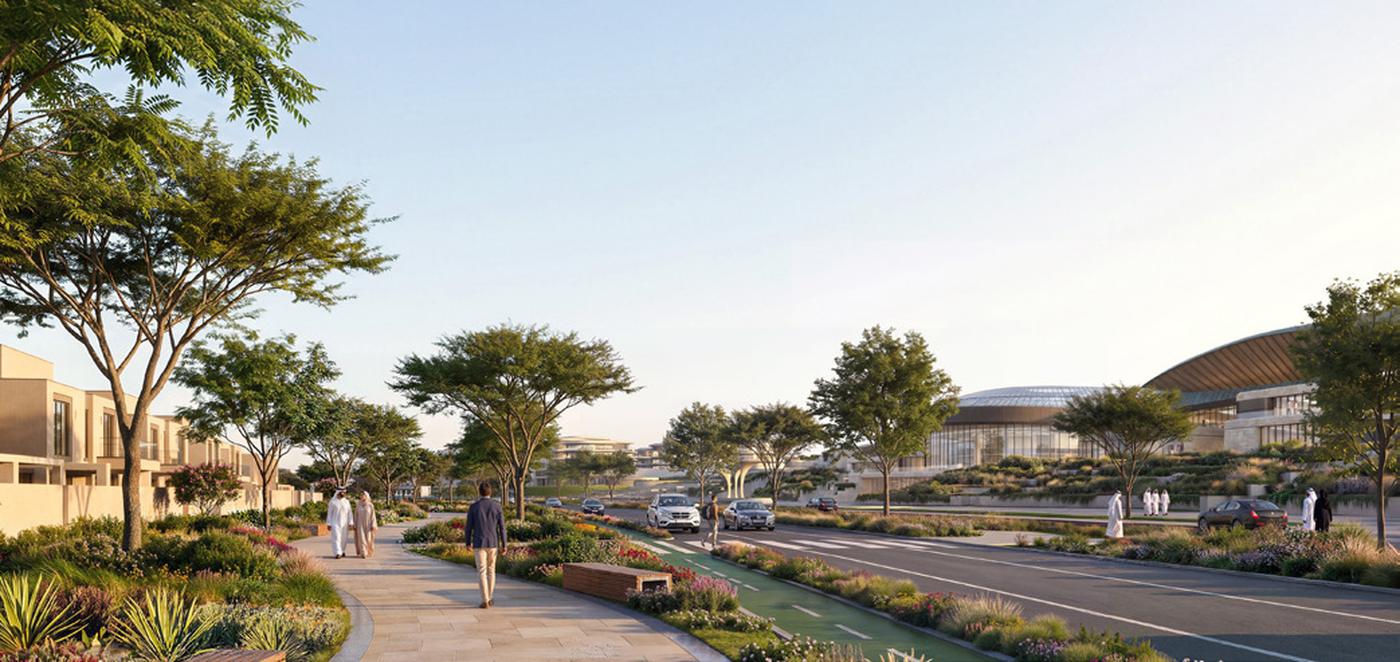
In the UAE we love a good mall, and this one is not a mall in the old sense. Modon is building a retail and dining destination on a walkable spine, which my information puts at 4.1 km, under a glass canopy. That is a fundamentally different proposition from a box with a car park.
A walkable spine means it works all year round. It means food and beverage, coffee shops, yoga and pilates, a creche and children's activities, all within a walk of the front door. It means a Saturday morning where the kids, the mother and the father all have somewhere to be. That is what turns a masterplan into a place people want to live, and it is the difference between a villa that is worth what you paid and a villa that is worth considerably more.
I think both the features and the desirability of this will land above the mall at Dubai Hills. That is my view rather than a published comparison, and you should weigh it as such, but I have walked both sites and I am comfortable saying it.
The 2.3 km figure in Modon's Wadeem Gardens factsheet is the spine through the residential community. The 4.1 km figure is the retail destination, which Modon has not yet published a factsheet for. They are two different things and I do not want them confused.
Three villas, and what each one costs by area
Built-up area is the villa itself. Plot is the land it sits on. Both are shown in the unit you picked at the top of the page, and every price converts into your currency. Modon publishes prices as a starting point, so treat these as the floor rather than the average.
What the mix tells you
Configure the villa
Bedrooms first, then the facade, then the layout. Everything further down this page follows what you pick here.
Modon's brochure offers the Arabian and the Modern facade on all three villa types. The gallery above shows both.
Exactly what you pay, exactly when
Modon offers the same villa two ways. Take the regular plan and you fund 45% yourself across the build. Take ADIB's finance and you fund 25%, the bank funds the rest, and you service interest only on what it has actually drawn. Same villa, same handover in June 2031, same gain. What changes is how much of your own capital sits in a building site for four years and eight months. Pick a route and a villa, and the whole schedule rebuilds around them.
—
Sixteen months where nothing is due, and a choice at the end of them
—
—
Bulk allocations are available. Every figure on this page multiplies straight through.
Anchored to Knight Frank's Abu Dhabi review for the year to June 2026 and ValuStrat's 2026 Dubai outlook. Drag the slider for anything in between.
When the appreciation actually turns up
Your money in, and ADIB’s, month by month
At handover you can take the mortgage from whichever bank in the market is offering the most competitive rate at that point. That is why the balance is not drawn on this chart.
The twenty-eight month gap
What ADIB puts in, and what it costs you
Two routes, one villa. On the regular plan you fund 45% across the build and no bank is involved until handover. On the ADIB route you fund 25%, the bank draws 20% to Modon in four tranches from December 2028, and you pay interest only on what has actually been drawn.
You need — to reserve and — in total by June 2028. On the ADIB route no further instalment is asked of you until October 2030, and your only outgoing is interest on what ADIB has advanced, peaking at — a month. That is exactly the window in which most families get their affairs in order for a mortgage.
You are putting — in, all in, against an asset priced at —. Whatever Hudayriyat is worth when this hands over, you have bought the right to that outcome for a quarter of the money, and ADIB takes none of the appreciation for funding the rest.
At handover, the mortgage is yours to place
You are not tied to ADIB, which funded the build. When the balance falls due you take the mortgage from whichever lender in the market is offering the most competitive rate at that point, on whatever term suits you.
That is four years and eight months from now. Rates, lenders and products will all have moved, and more banks are likely to be lending on this island by then than are today. Nothing on this page assumes a rate for it, and none of the figures above depend on one.
The bank advances — at handover, which is 75% of the price you agreed today and never grows with the villa.
Loan to value on the day it completes
- Debt, fixed at 75% of the purchase price—
- Value at your growth assumption—
- Loan to value—
- Your equity on day one—
- Growth needed to bring it under 50%—
What growth does to loan to value
The debt is fixed at 75% of the price you pay. Growth does not reduce it, it raises the value underneath it, so loan to value falls without you paying anything down. At no growth it stays at 75%.
Where the mortgage numbers come from
Modon's payment plan says the balance is subject to off-plan mortgage approval, and says nothing about the rate or the term. The rate on the slider is yours to set and the 25 year term is the UAE norm. Eligibility is checked again when the facility is actually drawn, which on this schedule is years away, so an approval today is comfort rather than a commitment.
And you are not tied to one lender at the end of it. At handover an owner can remortgage with whichever bank is offering the best rate in the market at that point. The facility that funds the build does not lock you into the mortgage that follows it. Nothing here is a mortgage offer.
What you keep by letting ADIB fund four instalments
The alternative is Modon's regular plan: 45% out of your own pocket across the build, no interest, and the 55% balance at handover. You end up owning the same villa either way. What changes is how much of your own money sits in a building site for four years and eight months, and how far that same money would have gone.
You put in 25%
You put in 45%
Your money out, both ways, month by month
What your own money actually earns
This is an option on Hudayriyat house prices in 2031, bought with 25% down and no carrying cost. The IRR below is calculated on your real dated payments, each one on the day it falls due, because your money goes in across four years and eight months rather than on day one.
| What you do at completion | Your cash in | Debt taken | Your equity | Profit on your cash | IRR | Profit on cash |
|---|
The number that matters
Produce a two page statement for your investor
Pick what the investor does at the end. The statement is built from the villa, the quantity, the currency and the area unit you have set on this page, and it carries the assumptions on its face so nothing is hidden.
Branded carries the logo, the contact panel and the credit line. White label carries your name only, with one 7pt credit line at the foot of each page. Leave the name blank and that line is omitted.
Opens a clean print view. Choose Save as PDF, and untick headers and footers for a document with nothing on it but the numbers.
Profit on your own cash, against annual growth
Every point of annual growth is amplified by the fact that you have only funded a quarter of the asset. Drag the growth slider above and the marker moves.
Everything Modon has released on Hudayriyat has sold out
This is the evidence base. Nine priced releases already sold on this island, shown per unit of built-up area in your currency, with Wadeem Gardens dropped in beside them so you can see where it lands.
| Release | Beds | Where | BUA | Price | Per unit |
|---|
Hudayriyat releases, per unit of built-up area
Where Wadeem Gardens sits
Al Naseem's rate is spread over a lot of terrace
Modon publishes Al Naseem's built-up area in two parts, internal and external. The external part is terrace and balcony. It is real space and it is worth having, but it is not the same thing as internal floor area, and on the chart above it is quietly dragging Al Naseem's rate down. Wadeem Gardens is quoted as a single figure with no external component broken out.
How this works, depending on who you are
If you are an investor
- This is a four year and eight month investment product. You are taking a futures option on Hudayriyat house prices at handover in June 2031, and on the ADIB route you are paying a quarter of the price for it.
- No tenants, no maintenance, no service calls, no utility bills, no voids and no agents. A buy-to-let makes you do all of that to earn the same appreciation.
- Your only carrying cost through the build is interest on what ADIB has advanced, peaking at — a month. ADIB takes none of the appreciation for it.
- You can sell from 20% paid, which is June 2028, twenty months in. At completion you choose again: take the mortgage and hold a finished villa on the best island in Abu Dhabi, or take the gain and move on.
- If the UAE is where you are tax resident and you hold it in your own name, there is no capital gains tax on the gain. Hold it in a UAE company and 9% corporate tax can apply. Take that from your own adviser, not from me.
If this is a home for your family
- Hudayriyat has been a cash market. This clarity on the finance is what opens it to families who plan properly, rather than only to families who happen to be sitting on the full amount.
- You need — to reserve and — in total by June 2028. After that, no further instalment until handover.
- On the growth you have set, loan to value on completion lands at —. That is a serious position to be in on a first mortgage.
- Two international schools, healthcare, six clubhouses and a walkable spine, on an island fifteen minutes from the airport and twenty from ADGM.
- UAE nationals receive a 5% rebate from Modon, non-transferable.
Modon has pioneered something here. A payment plan that asks for a quarter of the price, with ADIB funding instalments from 20% rather than waiting for 50%, and charging interest only while it does. That is not how plans work in this country. Families who plan financially and get this right are securing a lifestyle, and they are doing it with a loan to value most buyers never achieve.
My expectation is that more banks enter this market as developers and lenders catch on to what Modon has proved. When they do, the buyer pool on this island widens again, and that shows up in prices. I would rather be in before that than after it.
How buying with me works
No forms and no call centre. You deal with me from the first conversation to the keys.
- Detailed discussionsThe project, the financing, the market and the alternatives. Which type, which facade and floor plan, which cluster and garden aspect, how many villas, whether to use the ADIB finance, and whether Wadeem Gardens is the right place for this money at all.Start now
- I send you the sales offerFor the villa I would take if it were my money: the plot number, the cluster, the way the garden faces, the price and the payment schedule on it. Plot numbers run as one shared sequence across all three types, so the good ones are not obvious from a list.
- You book5% of the price plus the 2% ADM registration fee, a passport copy for every owner, and someone able to sign. If you are travelling, a power of attorney sorted in advance. This is the one that catches people out.On the day
- Then very little for a long time5% in June 2027, December 2027 and June 2028. With the ADIB finance, the bank then funds four instalments and you pay interest only on what it has drawn, until your final 5% in October 2030. On the regular payment plan you keep paying Modon directly instead.
Why the plot matters more than the date
Modon allocates on Hudayriyat, it does not queue, and every release it has brought to this island has sold out. Within one type the starting price barely moves, but the garden aspect does: at this latitude a north or east facing garden is the one you can sit in on a summer afternoon, and a south or west one takes the heat. That is the first thing I check for you.
Why I think this sells out, and what it looks like when it hands over
Hudayriyat is the best thing happening in Abu Dhabi. The defining decision was density: they could have packed half a million people onto this island and instead they have planned for something closer to 170,000. That single choice is why it will still feel like Hudayriyat in twenty years, and it is why I keep telling people that buying here is taking a stake in a place that will be world famous, not buying a villa off-plan from a housebuilder.
When Wadeem Gardens completes in 2031, the vision of this island stops being a set of renders. The arena is there. The retail spine is there. Two international schools, six clubhouses, healthcare, an office park and a waterfront promenade are there. I expect equestrian, polo, marinas and sailing to follow, though none of that is in Modon's published material, so take it as my expectation and not as fact. House prices reflect what a place has become, and by then this will have become something.
On this payment plan you are asked for a quarter of the price, with a bank carrying the rest from 20% rather than 50%, and charging you interest only while it does. If you have ever wanted a position on this island and found the cash requirement in the way, this is the release that removes the obstacle. I do not expect it to be available for long.
Twenty years across finance, offshore structuring and real estate, in London and now the UAE. I advise UHNW investors, family offices and VVIP clients on the best assets in Abu Dhabi and Dubai, and I tell them what I actually think.
Is the handover date confirmed? Open
Not in writing. Modon's payment plan never uses the word handover. What it does show, on both routes, is the 55% balance falling at month 56, June 2031. A developer takes the balance when it hands over the keys, so this page works to June 2031 throughout. I have asked Modon to confirm it and I would not treat it as fixed until they do.
Does the villa come with a pool? Published
With provision for one, not the pool itself. Modon draws a pool on every floor plan and every garden render, but the brochure's own footnote says the villa comes with pool provision only, and installation is by the owner, subject to approvals. Budget for it separately.
What is the difference between floor plan A and B? Published
The built-up area is the same on both. Option A puts the space into service: a larger service kitchen and laundry, a garden bathroom, and the bigger family room upstairs. Option B puts it into entertaining: a larger living and dining room and a ground floor majlis, with a master sitting area upstairs. Both are in the gallery under Floor plans, with every room size.
What exactly is the payment plan? Published
Two ways, and you choose. Plan A, the regular plan, 45 / 55. You pay 5% on reservation and at months 8, 14 and 20, then 10% in October 2029, 10% in October 2030 and 5% in April 2031. The 55% balance falls at handover in June 2031. No bank, no interest.
Plan B, with ADIB finance, 25 / 75. You pay the same first four instalments, ADIB commits 20% at month 24 and draws it to Modon in four 5% tranches at months 26, 32, 38 and 44 while you service interest only on what has been drawn, you pay a final 5% in October 2030, and ADIB mortgages the remaining 55% at handover. You fund 25%, ADIB funds 75%.
The finance is subject to ADIB's approval. If it is not approved, or you simply decide against it, you continue on Plan A. ADIB's decision falls at month 24, October 2028, and Plan A's next payment is not due until month 36, October 2029, so there is a full year between the two. Switch between the routes at the top of the payment plan section.
Do I pay any interest during construction? Yes, and this is the point
On the ADIB-funded route, yes, but interest only and only on what ADIB has actually advanced. It starts six months after the first ADIB instalment and steps up as each one is paid. On a five bedroom at AED 10.2m and a 4% rate that is AED 1,700 a month rising to AED 6,800, and about AED 88,000 across the whole build, which is under 1% of the purchase price.
Every mortgage in this country is capital repayment. Interest only, during construction, on an asset that is not finished, is not something this market has offered before.
Am I locked into that bank for the mortgage? No
No. At handover an owner can remortgage with whichever bank is offering the best rate in the market at that point. The facility that funds the build does not tie you to the mortgage that follows it.
What is the ADM fee and when is it due? Published
The Abu Dhabi Municipality registration fee is 2% of the purchase price and falls at reservation, alongside your first 5%. It is included in every figure on this page.
Can I sell before completion? Yes, from 20%
Yes. The threshold is 20% paid, which on this schedule you reach in June 2028, twenty months after reservation. From that point the villa can be sold on and your buyer steps into the remaining payment plan.
That matters more than it sounds. You realise the appreciation without ever having drawn a mortgage, and your total exposure to that point is four instalments plus the registration fee. Modon has not published the threshold for this release specifically, but 20% has been the position on every Hudayriyat release to date and it is what this page works to.
My own view is that selling at 20% is the weaker outcome. The best appreciation on an off-plan asset usually comes after handover, not before it. But knowing your exit exists before you need one is the point.
Do I need finance approval to book? No
No, and I would not let it hold up a booking. The mortgage does not come into play until 2031 and you will be assessed again at that point regardless of what any bank says today. If you want the comfort of a pre-approval now, I will arrange it, but book the villa first.
Can international buyers purchase here? Yes
Yes. Hudayriyat is a freehold investment zone open to all nationalities. The mortgage terms available to a non-resident will differ from those available to a resident, and that is a conversation with the bank rather than with Modon.
Is there anything in it for UAE nationals? Published
Yes. Modon gives UAE nationals a 5% rebate, and it is non-transferable.
What about capital gains tax? Context
The UAE levies no capital gains tax on an individual selling property held in their own name. Two things catch people out: hold it through a UAE company and 9% corporate tax can come into play, and if you are tax resident elsewhere your own country will usually still want to tax the gain. I am a broker, not your tax adviser.
What is the catch? My answer
The honest one: you are buying an asset that does not exist yet, on an island where nobody lives yet, and you are betting that Modon delivers what it has drawn. Their record on this island is that every release has sold out and that they build what they show. The mitigation is that your money goes in slowly, your carrying cost is a few thousand dirhams a month rather than a mortgage, and the full 20% is not committed until June 2028, by which time you will have watched them build for nearly two years.
The instalments are tied to construction milestones rather than to the calendar. Early works, commencement of infrastructure, substructure, 50% of the superstructure, the facades, completion. If Modon runs late, the milestone has not been hit and the instalment has not fallen due, so a delay costs you time rather than cash. That is the right way round, and it is not how every plan in this market is written.
Set against that risk is the size of the prize. At the end of this four year term there are very substantial gains to be realised by investors who believe in the future of Hudayriyat and Abu Dhabi, and you are buying that position with a quarter of the price and a few thousand dirhams a month.
WhatsApp me now for the live availability.
Booking is open and Modon allocates plot by plot, so the good ones go first. Tell me the type, the budget and how many villas, and I will come back with the villa numbers I would take if it were my money, garden aspect first. It takes one message. These are the four things you need in place when the villa is offered.
- Passport copyFor the buyer and any co-owner. Buying through a company, a copy of the trade licence too.
- 7% ready to move5% of the purchase price plus the 2% ADM registration fee. On a five bedroom at AED 10.2m that is —, and on a four bedroom at AED 8.7m it is —.
- Someone able to signIf the buyer is travelling, a power of attorney or an authorised signatory sorted in advance. This is the one that catches people out.
- Finance eligibility, only if they want itNot needed to reserve. The facility is checked again when it is drawn, so an approval today is comfort rather than a commitment.